You can still retire to the Canary Islands from the UK, but since Brexit it is a two-part job: first a Spanish residence permit, usually the non-lucrative visa, and then healthcare, which for UK state pensioners normally means registering an S1 form so the NHS pays for your Spanish care. Get those two right and the rest is familiar: a pension paid into a Spanish bank, a health centre down the road and a winter that never really arrives.
The simplest version, which suits many people, is not to move at all. A British pensioner can spend up to 90 days in any 180 here as a visitor, so a long winter of up to three months needs no visa, just a GHIC and travel insurance. Anything longer, and certainly a permanent move, means residence, and residence brings Spanish tax rules with it.
This page covers the retiree's angle: residence, the S1, pensions and tax, inheritance and where people actually settle. The general paperwork for any move, in the order you will meet it, is on our page about moving to the Canary Islands. Rules here come from GOV.UK, the Spanish Boletín Oficial del Estado and the UK–Spain tax treaty, and they are a starting point for a conversation with a cross-border adviser, not a substitute for one.
Swallow or resident: decide this first
Thousands of British retirees already spend the cold months in the islands without ever becoming resident. They come in November or January, stay under the limit explained on our page about the 90/180-day rule, and go home before it runs out. Our page on the Canaries for older travellers covers that way of doing it.
The swallow route keeps your NHS care, your UK tax residence and your home in Britain, and costs nothing in paperwork. Its limits are hard ones. Ninety days means you cannot stay from November to April. Overstaying can mean a fine and a Schengen entry ban. And if you spend more than 183 days a year in Spain, by whatever means, the Spanish tax office may consider you resident whether you registered or not.
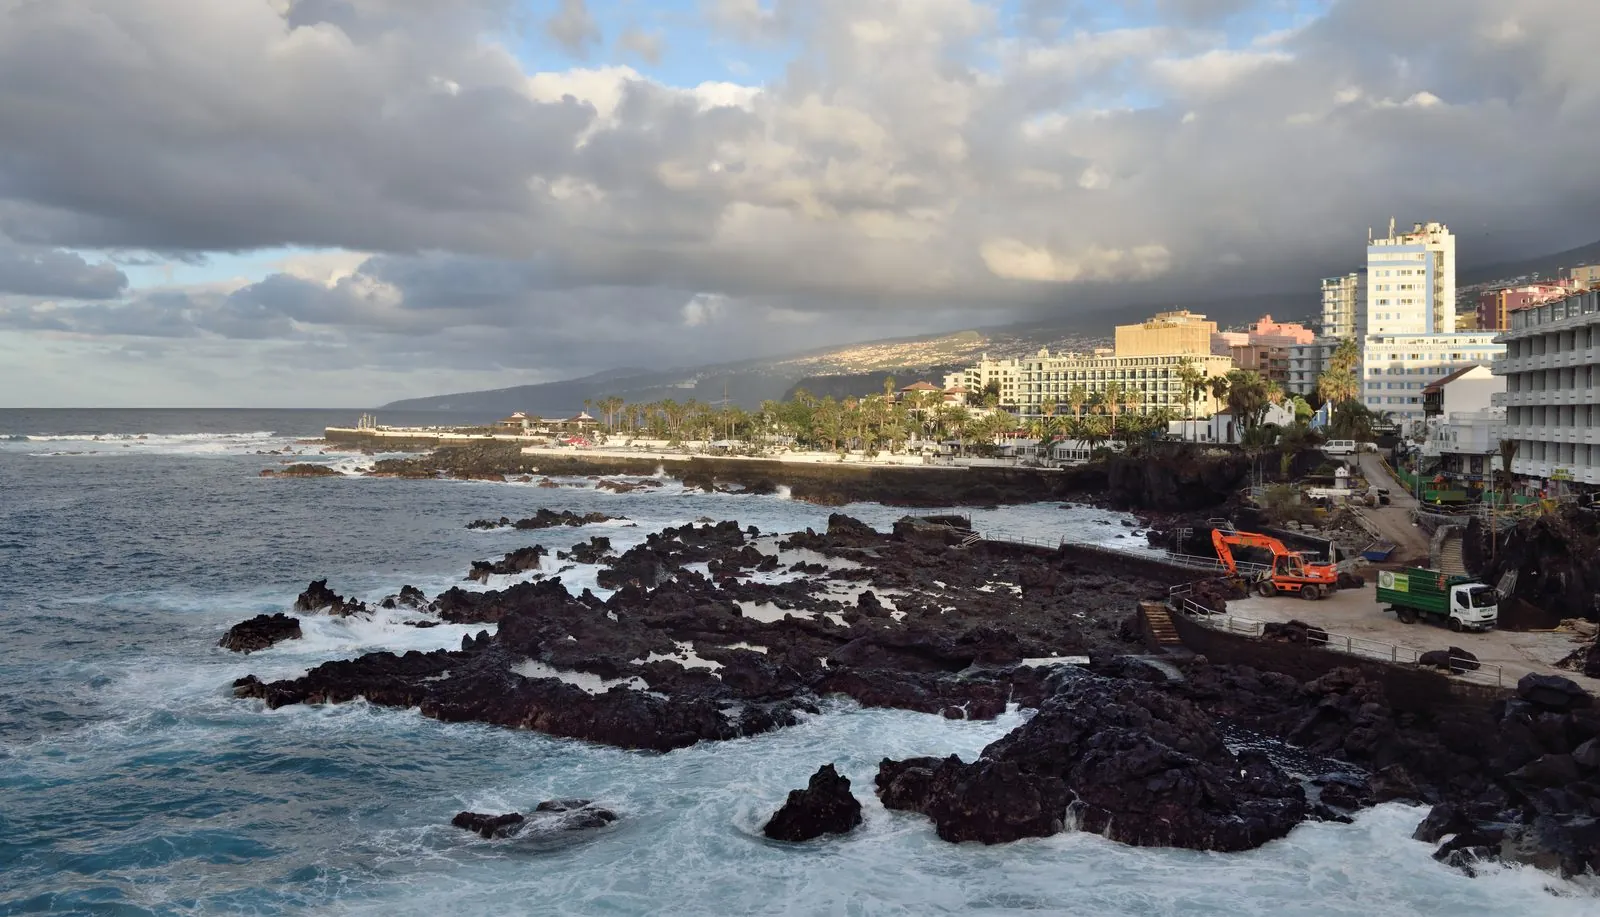
Photo: Cayambe · CC BY-SA 4.0 · Wikimedia Commons · scaled
Getting residence as a retiree
British retirees who were legally resident in Spain before 1 January 2021 are protected by the Withdrawal Agreement and should hold a TIE card, which GOV.UK calls "the only valid residency document listed in the Withdrawal Agreement". For everyone else the usual route is the non-lucrative residence visa, applied for in person at the Spanish consulate or visa centre covering where you live in the UK.
Spanish consular pages set the financial requirement at 400 per cent of the IPREM, a benchmark index fixed in the Spanish state budget, plus 100 per cent for each dependant such as a non-working spouse. Ask the consulate for the current euro figure. Pension income counts. You also need private health insurance from an insurer authorised in Spain that covers everything the public system covers, a criminal record certificate for the last five years and a medical certificate. The visa forbids paid work in Spain, which for most retirees is not a problem, but it does rule out a little part-time job in a bar.
Healthcare and the S1
An S1 is the form that makes the UK pay for your state healthcare in Spain. GOV.UK's guidance for UK nationals living in Spain says you may get one if you receive a UK State Pension or certain exportable benefits, and that with it you and your dependants are entitled to state healthcare "on the same basis as a Spanish citizen".
- Request the S1 application from the NHS Overseas Healthcare Services, which GOV.UK says is done by phone.
- Register the S1 at your local INSS office, Spain's social security institute, or through its online portal.
- The INSS sends you a Spanish social security number.
- Take that number to your local health centre to register with a family doctor.
GOV.UK adds that S1 holders also receive a UK-issued GHIC or EHIC for trips elsewhere in Europe. Prescriptions are under Spain's co-payment system, in which GOV.UK says residents usually pay between 10 and 60 per cent of the cost depending on their circumstances. If you return to live in the UK, you tell the NHS Overseas Healthcare Team so the S1 is cancelled.
Retiring before State Pension age leaves a gap. Without a UK State Pension there is no S1, so early retirees pay for private insurance for the visa and afterwards. After a year on the padrón they can join the public system through the Convenio Especial; Spain's Royal Decree 576/2013 sets that fee at €60 a month under 65 and €157 at 65 or over, and Convenio members pay full price for prescriptions. Budget for it until your State Pension starts and the S1 takes over.
Day to day, Spanish public healthcare in the larger islands is good, with big university hospitals in Santa Cruz, La Laguna and Las Palmas and a hospital on each of the seven main islands. Our page on pharmacies and medical care explains health centres, emergencies and the pharmacy system.
Your UK State Pension in Spain
This is one of the few areas where Brexit changed nothing. GOV.UK confirms that the State Pension increases each year if you live in the European Economic Area, which includes Spain. You claim it from the International Pension Centre, and it can be paid into a UK account or a Spanish one; GOV.UK notes a 0.39 per cent conversion charge on payments into an overseas account, and a choice of payment every four or thirteen weeks.
There is one rule that catches out people who split the year. GOV.UK says you must choose which country your pension is paid in, and that you cannot be paid in one country for part of the year and another for the rest. If you are half swallow and half resident, decide where you really live and tell the Pension Service accordingly.
Tax: which country taxes which pension
Spanish tax residence starts when you spend more than 183 days in Spain in a calendar year, or when your main economic interests are here. Article 9 of the Spanish income tax law adds that sporadic absences count as days in Spain unless you prove tax residence elsewhere, so trips home do not reset the count. Once resident, you are taxed in Spain on your worldwide income, and GOV.UK warns that you must declare assets held outside Spain.
The 2013 UK–Spain double taxation convention decides where each pension is taxed. Article 17 says ordinary pensions, which include the State Pension and private and workplace pensions, are taxable only in the country where you live, so for a resident that means Spain. Article 18 makes an important exception: pensions paid by the UK government for government service, such as civil service and armed forces pensions, are taxable only in the UK, unless you are both resident in and a national of Spain. Many retirees have one of each, and the paperwork has to reflect it.
Do not assume that the tax-free lump sum you can take from a UK pension is treated the same way in Spain, or that Spanish allowances mirror British ones. This is the single area where a cross-border adviser earns their fee, ideally before you draw any lump sum and before your first full year of residence.
Wills and inheritance
Spain taxes inheritances, but the Canaries are among the regions that relieve close family almost entirely. Article 24 ter of the Canarian tax code, as consolidated in the Boletín Oficial del Estado, gives a 99.9 per cent reduction of the inheritance tax due for heirs in Spain's first three kinship groups, which cover children and grandchildren, spouses, parents and grandparents, and close relatives such as brothers and sisters. Unrelated heirs, including some unmarried partners, may fall outside it.
Whether the Canarian rules apply in your case depends on where you and your heirs are resident and where the assets are, and UK inheritance tax may apply alongside. Most British residents make a Spanish will for their Spanish assets with a notary, in addition to a UK will. A lawyer can make sure the two do not cancel each other out.
Where retirees settle, and why
Retirees choose towns for the same handful of reasons: flat walking, sunshine in January, a hospital within reach, and flights home. A few places come up again and again.
- Los Cristianos in south Tenerife has a long, level seafront, reliable winter sun, a big British and Scandinavian community and Tenerife South airport close by.
- Puerto de la Cruz on Tenerife's north coast is cooler and greener, a real town rather than a resort, with more Spanish life and a short drive to the hospitals in La Laguna and Santa Cruz.
- San Agustín and the coast around Maspalomas in south Gran Canaria are quiet, sunny and close to the motorway to Las Palmas.
- Puerto del Carmen on Lanzarote has a flat promenade, plenty of English spoken and the island's airport ten minutes away.
The smaller islands appeal to retirees who value quiet over convenience, but specialist treatment often means a flight to Tenerife or Gran Canaria. Our page on the warmest island in winter compares the climate, and the cost of renting in each place is covered in our cost of living guide.
Renting before you buy
Most people who have done it say the same thing: rent for a year first. A flat that is lovely in February can be noisy in August, a hillside that looked charming may be a hard walk at 80, and you may discover you prefer the north to the south. A long lease also gives you an address for the padrón and the visa. Our page on renting long-term covers where to look, and if you do decide to buy later, our property guide sets out the taxes and checks.
Retiring here well
Decide first whether you want a long winter or a new home. Up to 90 days, you need only a GHIC, travel insurance and a flight. Beyond that, apply for residence from the UK, register your S1 with the INSS once you are here and your State Pension has started, and get cross-border tax advice before your first full year, especially if you have a government service pension or plan to take a lump sum.
Then choose the town with your future self in mind: flat streets, a health centre you can reach without a car, and a flight home that does not involve a change. Do that, and the islands remain one of the easiest places in Europe for a British pensioner to grow old in the sun.